The Warm Homes Loan Scheme can help reduce the cost of installing home energy improvements by lowering the interest rate on selected loans.
Eligible loans can get an interest rate reduction of up to five percentage points, helping to lower monthly repayments.
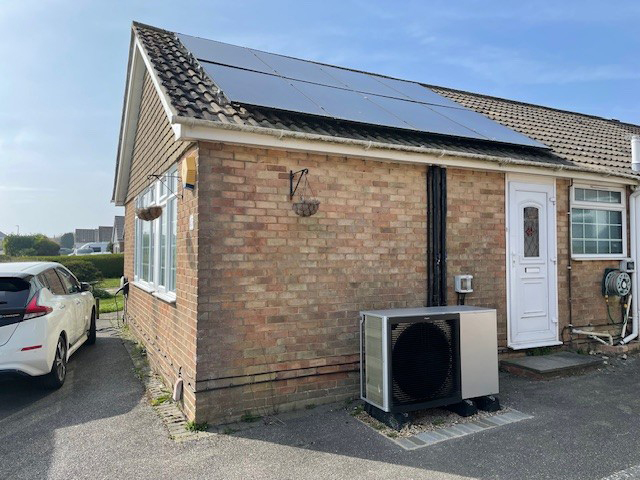
The scheme is available across the UK and can be used for improvements such as solar panels, heat pumps and battery storage.
What is the Warm Homes Loan Scheme?
Part of the UK Government’s wider Warm Homes Plan, the Warm Homes Loan Scheme helps homeowners and landlords with the cost of installing home energy improvements. The scheme works by lowering the interest rate of loans you take out with certain lenders.
This should include the costs for technology itself as well as related installation costs.
How much could I save with the Warm Homes Loan Scheme?
The Warm Homes Loan Scheme can reduce the interest rate of eligible loans by up to five percentage points (pp).
The exact reduction you could get depends on:
The lender: Each lender will have its own set of rates and rules.
The length of the loan: Longer-term loans may not reduce the interest rate as much as a shorter-term loan.
Here's an example:
Let’s say you wanted to borrow £10,000 and repay it over five years. You find a personal loan offering an 8% interest rate, so your repayments would normally be £201 a month.
If it was eligible under the Warm Homes Loan Scheme, the interest rate could go down to 3%. This would bring your repayments down to around £180 a month, saving you:
£21 a month
£252 a year
£1,260 over the length of the loan
What home improvements are covered under the Warm Homes Loan Scheme?
Each lender will have its own set of rules about what upgrades you can make, but it’ll likely include a combination of:
You don’t apply for the scheme directly. Instead, you:
Compare quotes for installation. We always recommend getting quotes from at least three MCS-certified installers. You can find local, certified installers using the MCS ‘find an installer’ tool.
Once you have a quote, compare loans from participating lenders. You can see a full list on the UK Government website.
Submit your loan application. The lender runs its own credit and affordability checks as with any other loan.
Arrange to install your home energy upgrades. Keep any paperwork as proof of purchase.
Start making repayments on the loan.
Be aware of scams
The introduction of new finance schemes often means an increased number of scammers. Stay alert and report anything suspicious. For more information, read our guide to spotting an energy scam.
No – only the person who owns the property can apply for the scheme. If you’re a tenant, speak to your landlord about your options.
Yes, you can. You can do this in two ways, depending on the lender’s eligibility rules:
Use one loan to fund a few different improvements.
Apply for more than one loan to fund different improvements.
Keep in mind that you need to be able to afford the repayments, whichever method you choose.
It depends.
Some lenders may partner with specific installers, so you wouldn’t be able to choose your own. But others might let you choose your own, as long as they’re certified with MCS.
No, you don’t need an Energy Performance Certificate (EPC), nor does your property have to be at a certain EPC rating to use the scheme.
Yes, it does. The Warm Homes Loan Scheme is UK-wide.
If you live in England, you may be eligible for a Warm Homes: Local Grant to make improvements. For more information, visit the UK Government website.
Energy Saving Trust is authorised and regulated by the Financial Conduct Authority (716195). It doesn’t provide or run the financial advice, products or services mentioned on this page, which is intended for information purposes only and doesn’t constitute financial advice.
Last updated: 3 November 2026
Tell us where you live
Get the most relevant content from Energy Saving Trust by telling us where you live